“Some say the second China shock is looming. But it’s already here. It shows in our communities and factories across our Union.” The words of the president of the European Commission, Ursula von der Leyen, during her State of the European Union address, serve as a stark reminder of what is at stake when the European Union (EU) discusses industrial policy.
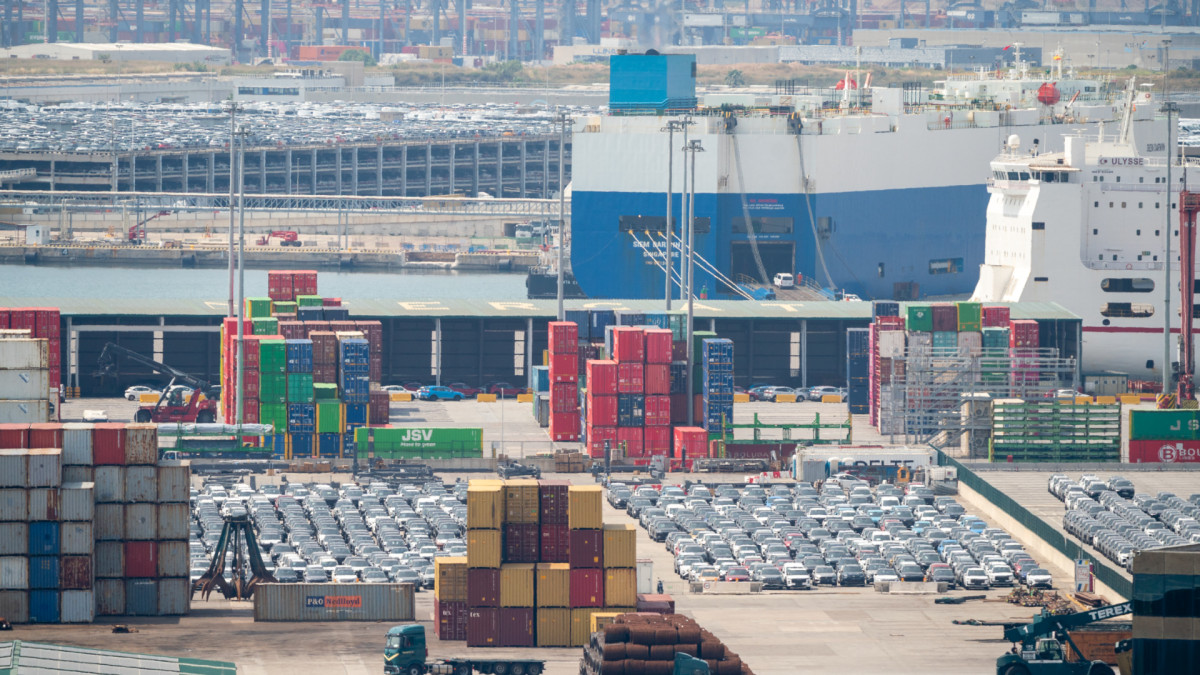
Chinese overcapacity is increasingly pricing out European manufacturers in the Single Market, resulting in plant closures, job losses, and economic downturn. It isn’t only about the EU’s daily €1 billion trade deficit with China: this situation also creates potentially dangerous dependencies in some of the EU’s most strategic sectors. The EU is responding to this challenge through both trade and industrial policy. At the core of this response lies the Industrial Accelerator Act.
“Chinese overcapacity is increasingly pricing out European manufacturers in the Single Market”
This Act is the most important piece of legislation of this mandate for the EU’s strategic industries. Its aim is to condition access to EU taxpayer money, via public procurement and other forms of support (bonuses, social leasing schemes, auctions), on a degree of local production. It concentrates on a handful of strategic sectors, including steel, cement, electric vehicles, and cleantech.
It seeks to reserve a portion of the market for low-carbon materials, such as steel, cement, and aluminium, and for cleantech, such as batteries, heat pumps, or wind turbines. It does so by establishing different criteria — primarily CO2 emissions during production and Made-in-Europe rules — to ensure public funds back EU-made products in specific sectors. This “lead market” approach could address a crucial challenge for the EU’s industry by creating predictable domestic demand for low-carbon materials and cleantech, reducing the pressure from Chinese overcapacity.
The Act has enjoyed wide-ranging support from the EU’s industrial sectors, from steelmakers to cement producers, automotive manufacturers and suppliers, cleantech companies, unions, and many others. Its demand signal could be pivotal for some of the continent’s industrial leaders. Battery gigafactories, such as the PowerCo facility under construction in Sagunto (Valencia), and low-carbon steel plants, like Hydnum in Puertollano, need predictable demand to scale up production and become more competitive.
“Its demand signal could be crucial for some of the continent’s industrial frontrunners”
The Act also outlines measures to speed up permitting for industrial plants in selected sectors and to condition certain foreign direct investments (FDI), ensuring they create local jobs and facilitate technology transfers, with outcomes such as shared ownership. A notable example is the Stellantis-CATL joint venture in Zaragoza, based on a 50‑50 ownership structure and planning to hire 4,000 local workers. The European Commission’s proposal, published in March, is currently being negotiated in the European Parliament and the Council. Adoption could occur in late 2026 or during 2027.
The goals of this Act — supporting the EU’s strategic industries through domestic demand, speeding up permitting, and conditioning foreign investment to maximise positive effects — have earned broad support among national governments and political parties. Yet, disagreements persist over the Act’s details, which can determine the policy’s success. Indeed, the industry requires a clear demand and investment signal to scale up manufacturing in Europe — a signal that cannot arise from half-measures and good intentions.
“The industry needs a clear demand and investment signal to scale up its manufacturing in Europe — a signal that cannot come from half-measures and good intentions”
The Commission’s proposal, issued in March 2026, represents a political compromise that has curtailed potential industrial impact. It proposes numerous flexibilities, limits its core measures to a very narrow slice of the market, and broadens its Made-in-Europe criteria to a wide range of third countries. This risks producing a weak text with only limited impact on demand, encouraging investment in third countries rather than in the EU.
What does “Made in Europe” mean under the new law?
A central point of contention has been the geographical scope of the Act. Pinpointing which countries should be included in the “Made-in-Europe” definition is far from straightforward, as some governments want all trading partners included, while others prefer limiting it to EU members. The current proposal would encompass the 27 EU member states, plus countries that have signed a free trade agreement or a customs union agreement with the EU, or are parties to the WTO’s Agreement on Government Procurement, depending on the type of public intervention and the applicable conditions. In total, roughly 90 countries.
For the Act to be impactful, the Made-in-Europe definition cannot encompass too many countries, especially those that could undermine the EU’s competitiveness. Reciprocity for European companies abroad is a key factor — most EU trading partners actively employ local-content policies to support their own industries. It is also essential to implement measures that curb circumvention and prevent dominant nations from investing in countries included in the “Made-in-Europe” framework to export to the Single Market while benefiting from public support.
“To be impactful, the Act’s Made-in-Europe definition cannot include too many countries, especially those that risk undermining the EU’s competitiveness”
Indeed, Chinese foreign direct investment has surged in several EU neighbourhood countries in recent years, including Morocco, Serbia, and Turkey, particularly within sectors covered by the Industrial Accelerator Act. This could pose a risk that Chinese companies produce batteries, EVs, and other cleantech in these countries for export to the EU, thereby undercutting the policy.
Negotiations in the European Parliament and Council
The co-legislators, namely the European Parliament and the Council, are now shaping their negotiating positions on the text. In the European Parliament, the draft report prepared by members of the Socialists & Democrats, Renew, and Greens groups contains numerous measures intended to reinforce the Act. Amendments proposed by the various groups signal broad alignment among the centrists on the Act’s priorities.
The European People’s Party is showing significant division: some of its members have filed an amendment to reject the Act entirely, while its shadow rapporteur in the ITRE committee is proposing amendments to strengthen it. The Spanish delegation within the party appears broadly supportive, and seeks to bolster its most critical provisions. Overall, the European Parliament is poised to enter negotiations with a strong mandate in favor of a truly impactful Act.
In the Council, negotiations are ongoing to define the Made-in-Europe criteria. The lead-market approach within the Act would benefit the entire EU by driving growth and jobs, especially in countries endowed with significant manufacturing capacity, such as Czechia, Slovenia, Slovakia, Hungary, Poland, or Germany. Nearly all national governments have expressed backing for the Act’s objectives, but discussions continue over certain details. Specifically, the geographic scope of the Made-in-Europe criteria and some of the flexibilities proposed by the Commission are central to the talks. Spain has played a pivotal role in this debate. As a major cleantech industrial hub, the country stands to gain considerably from the Industrial Accelerator Act.
A preliminary Franco-German agreement on the automotive portion of the Act has been reached. Drafts indicate both countries have found common ground on strict Made-in-Europe criteria, with an option to include additional countries. This agreement could unlock the next steps toward adopting the Act, provided it guarantees support for key parts of the value chain (including batteries) and broadens its approach to the other sectors of the Act.
“This agreement could unlock the next steps towards adopting the Act, provided it ensures support for strategic parts of the value chain (including batteries)”
Both the Commission and the Council have signaled their intent to conclude negotiations on this Act before year’s end. While that deadline may be optimistic, it is clear that the EU aims to adopt an Industrial Accelerator Act in the months ahead. This regulation stands at a crossroads for the EU’s strategic industries. Its ultimate shape and adoption could significantly influence the business case for investing and manufacturing within the EU over the coming decade. With 2027 set to be a year of national elections, there is a pressing need to enact a robust industrial policy that meets the demands of the EU’s strategic sectors.