The economic effects of artificial intelligence are beginning to surface in concrete tasks, yet they have not yet shown up in overall productivity metrics. Diane Coyle, Bennett Professor of Public Policy at the University of Cambridge and one of the confirmed speakers at La Toja Forum 2026, attributes this to the way companies operate: before benefits can be captured, organisations must overhaul their workflows and business models. She also rejects the most extreme predictions: “I don’t myself think it will be a job apocalypse of the kind that some of the AI leaders have been talking about”.
In conversation with Agenda Pública, Coyle explains how the technology could affect youth employment, how productivity gains might be distributed, and Europe’s lag behind the United States. For the continent, the upside lies in data, applications and research, although a heavy dependence on technology also creates geopolitical risks. The crucial question, she warns, will be who ends up capturing the value created: “We are in a situation where a very small number of people are making a lot of money”.
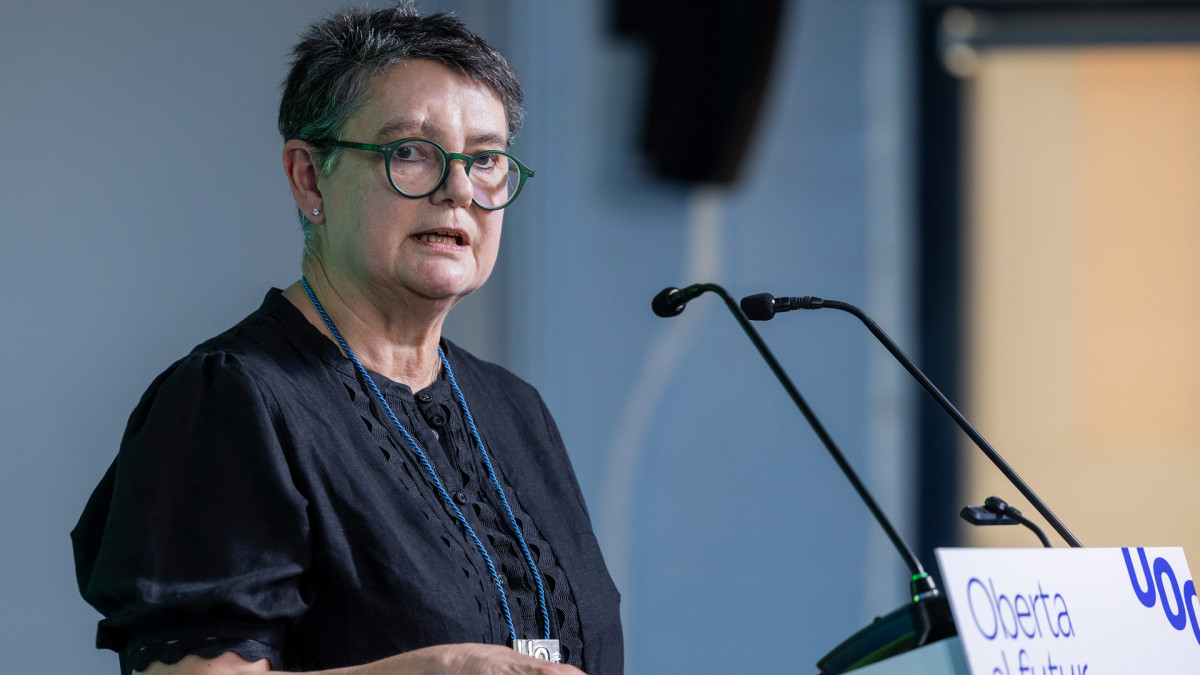
Last May, Coyle was awarded an honorary doctorate by the Universitat Oberta de Catalunya. Photo: UOC
Do you think we are overestimating the economic impact of AI, or is it simply that we have not seen the real effects yet?
It’s a bit of both. It depends on what you mean by AI. There is a lot of buzz around artificial general intelligence and conscious AI. I think those notions are overblown. If you view AI tools as an evolution of machine learning or earlier digital tools, then the question is whether it is still early to observe the effects.
There are now many studies showing that for individual tasks at work, AI can save a great deal of time. People can work faster and do their jobs better, but that does not yet translate into organizational productivity gains. And that, to me, signals that we need to see the kind of reorganisation of workflows and new business models that emerged with the advent of digital platforms in the late 2000s.
“We need to see the kind of reorganisation of workflows and new kinds of business models that we saw in the late 2000s when digital platforms came along”
If that proves correct, we should start observing measurable macro-level productivity improvements from AI in the next two or three years. But such organizational change comes at a cost, is slow, and people resist it, so it always takes time. It is much slower to reform institutions than to upgrade technology.
That was actually my next question. Are we asking the wrong questions when we focus on AI destroying jobs? Should we be paying more attention to who will capture the productivity gains that AI creates?
I think I agree with that. The evidence about young people’s jobs is somewhat tentative because you need to disentangle it from business-cycle effects. There was a surge in hiring and retention after COVID, followed by a natural downturn in entry-level roles.
It is true that the kinds of firms that hired many young workers—such as accounting firms or law firms—have reduced that level of hiring, but not entirely, because they recognise that you need young people to nurture experienced, senior staff over time. So they are concerned about those career trajectories and about how people gain experience if you do not hire them when they are young.
That said, the character of jobs will certainly change and there will be disruption. I have been contemplating the legal services sector as well due to evidence from Google’s Atlas study and other tech companies indicating extensive AI use in administrative tasks.
Two friends of mine recently needed probate for their parents’ wills. One paid £12,000 consulting a lawyer, while the other obtained it for free using ChatGPT. That points to a potential disintermediation. We saw similar patterns in previous waves of digitalisation with online banking, online taxis, Uber, Airbnb, and so on.
“Two friends of mine recently had to get probate for their parents’ wills. One paid £12,000 using a lawyer, and the other got it for free using ChatGPT”
All of these disruptive models affected real sectors of the economy. So I expect to see some of that kind of disruption. I don’t personally think it will be a job apocalypse, as some AI leaders have claimed. I believe they are exaggerating.
And what could governments do to ensure workers benefit from these changes?
We know from previous waves of automation that governments, on the whole, are not very good at helping people navigate such transitions. Some are better than others. People often point to Denmark’s flexicurity model, which provides generous support as people retrain and transition to new jobs.
So we can learn from past policy missteps. Another set of questions concerns who captures the value generated by data that firms accumulate. If my employer creates a digital twin of me and earns one and a half times as much work, what portion of that goes to my pay raise?
There are allocation questions that go back to fundamental issues of countervailing power in the labour market: what bargaining power do workers have, and to what extent will governments support them in capturing a share of the productivity gains?
We’ve spent years discussing Europe’s widening productivity gap with the United States. But to what extent is that diagnosis about technology itself, and how much about investment, scale, and other structural factors?
I think a large part relates to those very structures: regulatory barriers that hinder entry into new markets.
If you consider why Airbnb or Uber succeeded, it was largely because there was regulatory arbitrage. Taxi markets were heavily regulated and expensive, leaving an opening for a tech company to enter.
“If you think about why Airbnb or Uber did so well, it’s because there was regulatory arbitrage. Taxi markets were highly regulated and expensive”
There are also issues like the cost of laying off workers. Of course, we want to protect people, but the costs in some countries are excessive. It varies significantly. In Scandinavia, that isn’t the case at all, and those economies are among the most dynamic and high-tech in Europe.
Meanwhile, in Germany or France, it can be extremely costly to start a venture and then watch it fail a year later, which is what happens with many tech startups. The expenses involved in launching such ventures are very high indeed.
As a result, the return that venture capitalists demand to invest in these startups is several percentage points higher than in the United States or in Scandinavia.
ARTÍCULOS RELACIONADOS
Professor Robert Kaplan on a previous visit to Spain.Jorge Gil / Europa Press
Prior to joining OpenAI, Dean Ball served as Senior Policy Advisor for Artificial Intelligence and Emerging Technology at the White House Office of Science and Technology Policy.Archive
Is Europe in danger of becoming a very sophisticated consumer of technology from other countries rather than building genuine technological capability of its own?
Well, importing services from abroad isn’t inherently bad if you can export services of your own. And there are Chinese models that offer, for most applications, results comparable to American ones. So there is competition among frontier AI models.
“It’s not a bad thing to import services from other countries if you have services of your own that you can export”
European nations therefore need to identify their advantages. A clear one is data and applications. In fact, this mirrors a Chinese approach as well: focusing not only on frontier models but also on practical applications of AI.
Thus, if we possess excellent applications or, as Europe does, first-rate AI researchers, we have a stake in a positive global AI economy.
I think the concern here is more geopolitical than strictly economic. To what extent does an unpredictable American administration, which exercises legal authority over what AI companies can do, create vulnerabilities or not?
There’s a familiar critique that the United States innovates, China scales, and Europe regulates. Do you think that diagnosis is fair, or does it confuse regulation with other problems like insufficient investment and market fragmentation?
I think that view is somewhat simplistic. Both the United States and China enjoy the enormous advantage of scale. The venture-capital market and the size of their domestic markets matter a great deal.
Europe could do more to lower barriers to both production and demand, thereby increasing opportunities to scale. Yet I fear we may be talking Europe down too much. There are genuine research strengths here.
You could imagine a European university becoming the hub for creating energy-efficient technologies, for instance, which would become a significant competitive advantage. This is a dynamic field, and the research frontier advances rapidly.
There are plenty of opportunities. The challenge is to identify which barriers entrepreneurial firms cannot overcome. I’d prioritise removing obstacles that prevent data-driven innovation and other regulatory barriers that hinder the growth of legal tech or health tech startups.
And all of us, including the UK, share a need to dismantle those barriers.
If you had to place a bet today on who will capture the largest share of the economic gains from artificial intelligence — workers, companies, or governments — where would you put your money?
It’s a tough call. I believe, in the end, benefits must accrue to people. After all, these are general-purpose technologies that ultimately serve the broad market.
You need demand for the technology to be used. The alternative—at least in the medium term—could be upheaval. We are in a situation where a very small number of people are making a lot of money.
Unless the value is spread more broadly, we risk politically turbulent times. So I don’t know whether we’ll take a smooth path or a stormier one, but I’m convinced that, eventually, the gains from artificial intelligence will reach people in general.
Thank you so much. See you at La Toja.
En alianza con