Europe has savings. What it lacks, at least to the same extent as the United States, is a culture capable of transforming that savings into productive investment. The difference seems financial, but its consequences are industrial, technological and, increasingly, geopolitical. At a moment when the European Union needs to mobilize capital to finance its energy and digital transition, scale innovative companies and reduce strategic dependencies, keeping a substantial part of households’ wealth out of capital markets has ceased to be only a matter of personal profitability.
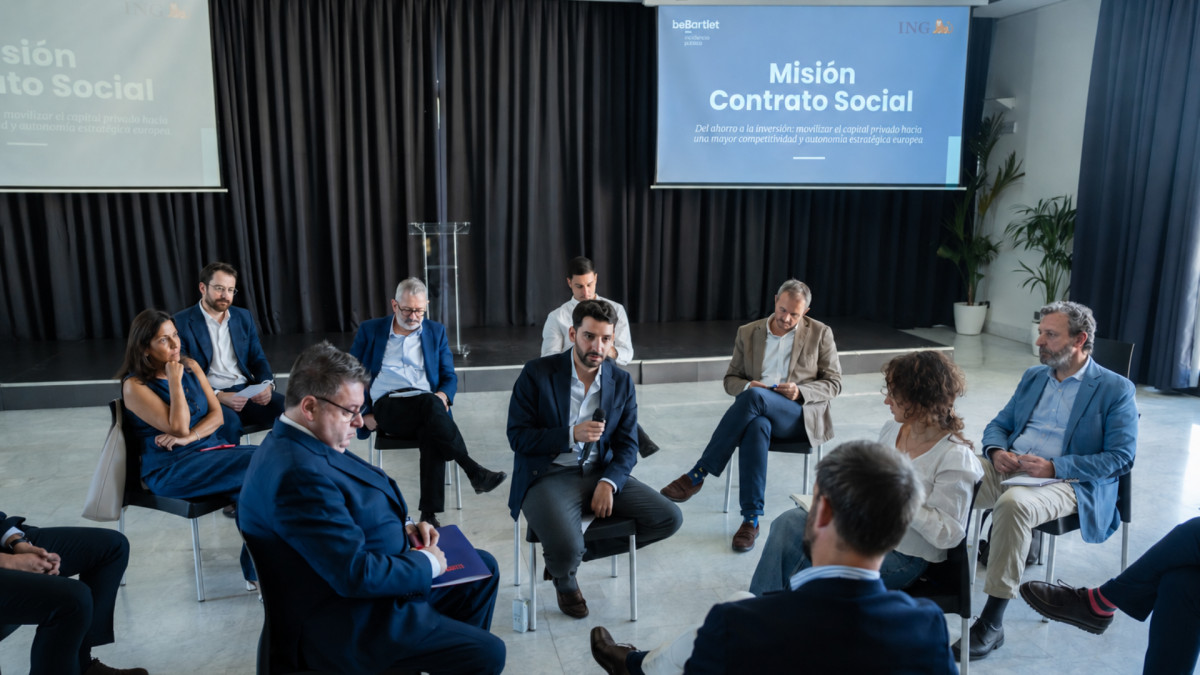
That was the starting point of the ninth edition of Misión Contrato Social, organized by beBartlet with the support of ING under the title From savings to investment: mobilizing private capital toward greater European competitiveness and strategic autonomy. The gathering, held recently at the Circulo de Bellas Artes in Madrid, brought together institutional, political, business, civil society and financial sector profiles.
The household saving rate stands at 14.3% of gross disposable income, against an investment rate of 8.5%. About ten trillion euros remain in cash and low-yield deposits, while 80% of euro-area households do not own shares or any other market instrument.
“Maintaining a substantial portion of households’ wealth outside the capital markets has ceased to be solely a question of individual profitability”
The comparison with the United States helps to size the gap. The report itself notes that in the eurozone, deposits and cash represent around 33% of households’ financial wealth, compared with 12% in the United States; market instruments — funds, ETFs, stocks or bonds — account for 20% in Europe and 50% in the United States. The question, therefore, is not that Europe saves little, but what it does with what it saves.
The session tackled many of the keys present in ING’s ‘Insight’ on ‘From saving to investing’. Photo: ING
The Price of Prudence
Economics professor Santiago Carbó summed up this anomaly with a single phrase: “the price of prudence”. For years, keeping money in very conservative products could be seen as a virtually neutral decision. In an inflationary environment, that is no longer the case.
The numbers illustrate the magnitude of the problem. European households save around €1.4 trillion per year, roughly double that of Americans, but about €300 billion annually ends up financing the U.S. economy. The estimate suggests that European households would have €1.17 trillion more in wealth today if only a quarter of their deposits had been invested in other assets since 2020. The cumulative loss amounts to roughly 7.4% of the eurozone’s GDP.
“European households save around €1.4 trillion a year, roughly double what Americans save, yet about €300 billion a year ends up financing the U.S. economy”
Here is where the link to European competitiveness diagnoses appears. The problem of domestic savings cannot be separated from the difficulty of financing innovative companies, infrastructure and strategic technologies. Europe needs some €800 billion more in annual investment, yet a substantial portion of its financial resources remains in low-return assets or ends up funding other economies.
Spain, however, “has already started to turn,” Carbó noted. The share of deposits and cash in the financial savings of households has fallen from 51.2% in 1995 to 33.3% in the first quarter of 2026, while collective investment institutions reached a historic high of 17.3%. In the last year, investment funds attracted €48.148 billion. The movement exists, although perhaps not yet at the speed required.
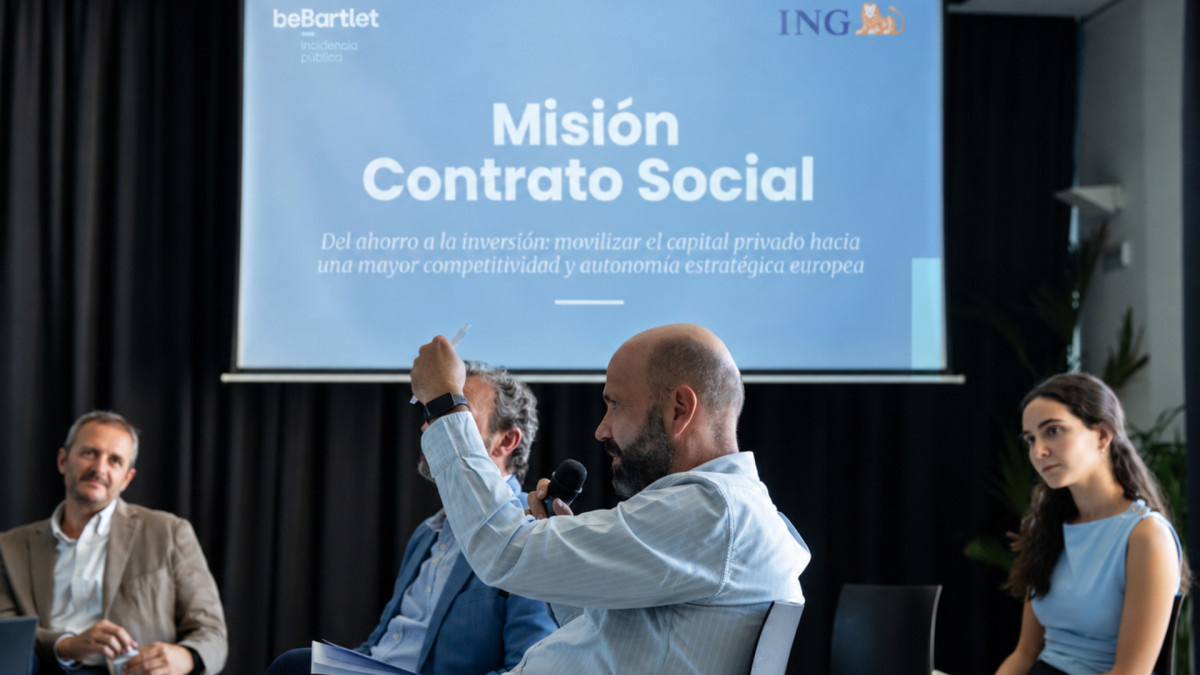
The various participants in the event offered new approaches to improve European saving. Photo: ING
Knowing Money Loses Value Isn’t Enough
The Spanish case shows a second paradox: the gap between knowledge and behavior. 62% of citizens know that idle money loses value, but 63% are not investing currently. Sixty-five percent continue to prefer a low but guaranteed return, and among those who do not invest, four out of ten say they could. The greatest conversion potential lies among those aged 25 to 44.
“62% of citizens know that idle money loses value, but 63% do not invest currently”
This gap threaded through much of the discussion. Pablo Porres, ING’s Head of Private Banking and Investment, grouped the causes into three broad categories: cognitive, physical and regulatory barriers. Fear, ignorance and risk aversion coexist with obstacles such as the perception of not having enough wealth and with regulatory and tax elements that can reduce the attractiveness of certain products. The result, he summarized, is that “Spanish people are leaving money on the table compared with other geographies”.
The data make the diagnosis concrete. Risk aversion, cited by 56%, appears as the main barrier; followed by lack of knowledge at 43%; insufficient wealth at 28%; taxation at 27%; and digital procedures at 21%. Against these, the analysis points to five levers: corporate contributions that incentivize saving, sustained financial education, small periodic contributions, long-term investment accounts and simple digital processes.
The Economics professor Santiago Carbó explained the shift in the savings paradigm during inflationary periods. Photo: ING
Education, Initiative and Trust
Financial education emerged as one of the clearest consensus points of the gathering. The discussion recalled that barely 18% of citizens have a high level of financial literacy, and attention was drawn to European efforts to spread best national practices. Among the examples was Slovenia, where educational programs incorporate practical and competitive mechanisms for students to apply what they have learned.
The conversation pushed the argument further. It is not enough to teach financial concepts: initiative must be fostered from an early age. The American “lemonade culture” — children doing small tasks to earn their first income — served as a metaphor for a deeper cultural difference, advocating learning to undertake as early as possible.
The discussion also introduced a distributive dimension. Financial education limited to private or voluntary initiatives risks reaching mainly those who already have more resources. Hence the defense during the gathering of a more transversal training, capable of reducing information asymmetries between citizens and financial institutions.
“Financial education limited to private or voluntary initiatives risks reaching mainly those who already have more resources”
But lack of knowledge explains only part of the problem. The other part is trust. During the gathering, Spanish risk aversion was linked to a culture traditionally oriented toward home ownership as well as to the fallout from the financial crisis. It was suggested that the relationship of trust between the banking sector and much of society had been broken then and has not yet been fully rebuilt.
The discussion also emphasized transparency and the need to strengthen trust in financial institutions, though it added a nuance: money deposited in banks is not economically idle, since institutions transform it into credit and investment. The question, therefore, is how to improve that channeling and what financial structure enables mobilizing capital without transferring undue risks to the small saver.
Financial education also connected to equality and the economic security of families. In an ecosystem where many young people receive recommendations about cryptocurrencies and other assets through social networks, support for an initiative grounded in knowledge rather than “hype” was advocated.
The challenge is precisely to avoid a false dichotomy: promoting investment does not equal promoting speculation. To convert savers into investors, it is necessary to simultaneously increase their capacity to assume risk and their ability to understand it. Simple products, transparency, supervision and advisory services are, in this regard, prerequisites for expanding participation in the markets.
The Economics professor Santiago Carbó explained the shift in the savings paradigm during inflationary periods. Photo: ING
A Matter of Strategic Autonomy
The conversation took on a broader scale when it ceased to focus exclusively on households. The spotlight shifted to Europe’s loss of technological sovereignty and the difficulty of financing innovative companies with volumes comparable to those available outside the continent.
The question is especially relevant in areas such as artificial intelligence, semiconductors or quantum technologies. It is not enough to mobilize the small saver: banks, large companies, venture capital funds and private equity also have the capacity to move resources toward higher value-added sectors. Europe has knowledge and creates companies, but many find the capital needed to scale outside its borders.
That is where the financial issue becomes geopolitics. When a European company needs to relocate to the United States to grow, Europe loses not only an investment; it can lose intellectual property, skilled employment, productive capacity and technological autonomy. The goal is, therefore, not merely for Europeans to invest more, but to build an ecosystem capable of turning European capital into European growth.
“When a European company needs to move to the United States to grow, Europe loses not only an investment but skilled employment, technological autonomy, etc.”
In this sense, two profiles with different needs were distinguished. For the small investor, support from financial institutions and accessible products are essential. For high-growth startups, traditional bank financing may be insufficient: they need venture capital and markets deep enough to scale without leaving Europe.
This need leads to another structural problem highlighted during the discussion: the fragmentation of European capital markets. A Union aiming to mobilize hundreds of billions of euros in additional annual funding requires more integrated markets capable of providing financing for different company profiles and risk levels.
The discussion also stressed transparency, accountability, security and the stability of rules as essential elements to build trust. Carlos Martos, ING’s Head of Investment Products, focused on the opportunity represented by those four in ten non-investors who would be willing to start. For the financial sector, he argued, that means stopping talking solely about products and starting with the client’s needs, goals and life horizons.
Throughout the conversation there was opportunity to place perspectives as varied as big banks, companies or families. Photo: ING
From Saving to Participation
Thus the gathering left three closely connected planes. First, European households save a lot but participate little in markets and thereby forgo a portion of the potential returns on their wealth. Second, education, trust, accessibility and protection turn out to be decisive to broaden citizens’ participation in investment. Finally, Europe needs a larger share of its capital to finance its own companies, technologies and strategic infrastructures.
“Europe needs a greater share of its capital to finance its own companies, technologies and strategic infrastructures”
The key lies in combining prudence and investment, expanding options so that citizens and businesses can make informed choices within a system that is understandable, flexible and safe, without taking on unnecessary risks. Financial education, simple products, supervision, public-private collaboration, more integrated capital markets and sufficient funding for innovative firms were among the elements that shaped this common ground.
The European paradox is that part of the capital needed to finance its transformation already exists. It lies in the hands of Europeans themselves. Getting it to circulate more effectively will be key both to improving the future profitability of European savings and to boosting the growth of strategic companies and technologies and strengthening the Union’s ability to finance its own priorities.
In alliance with: