“Some say a second China shock is looming. But it is already here. Its effects are felt in our communities and factories across the Union.” These words from European Commission President Ursula von der Leyen, spoken during the State of the Union address (SOTEU), harshly remind us how much is at stake as the European Union debates industrial policy.
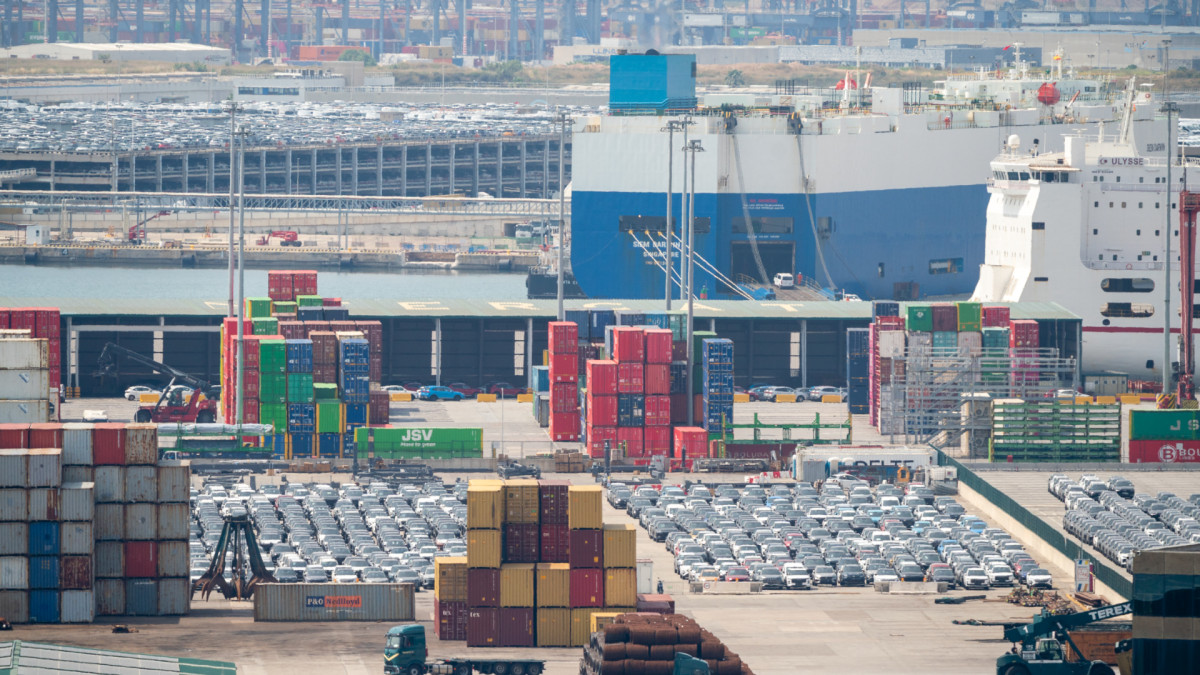
The Chinese overcapacity is pushing European manufacturers out of the single market by driving prices downward, leading to factory closures, job losses, and a deterioration of economic activity. The problem goes beyond the EU’s daily trade deficit with China of €1 billion; it also generates potentially dangerous dependencies in some of Europe’s most strategic sectors. The EU is responding through its trade and industrial policy. One of the central initiatives of this response is the Industrial Accelerator Act.
“The Chinese overcapacity is pushing European manufacturers out of the single market by driving prices down”
This regulation is the main legislative initiative of this legislature for the EU’s strategic industries. Its aim is to condition access to funds provided by European taxpayers to compliance with specific local production requirements, both in public procurement and in other forms of support — bonuses, social leasing programs, or auctions. It focuses on a limited number of strategic sectors, including steel, cement, electric vehicles and clean technologies.
The regulation seeks to reserve part of the market for low-emission materials, such as steel, cement, and aluminum, and for clean technologies, such as batteries, heat pumps, and wind turbines. To achieve this, it sets various requirements, mainly related to CO₂ emissions during manufacturing and the European origin of products, in order to ensure that public funds are directed to products manufactured in the EU in certain sectors. This policy of creating “pioneer markets” could help solve one of the main problems of European industry: the lack of a predictable domestic demand for low-emission materials and clean technologies. In this way, it would also relieve the pressure from Chinese overcapacity.
The regulation enjoys broad backing from European industrial sectors, from steel and cement producers to car manufacturers and suppliers, clean-tech companies, unions, and many other stakeholders. The prospect of a stable demand could prove decisive for some of Europe’s most advanced industrial companies. Battery gigafactories, such as PowerCo’s plant in Sagunto (València), and low-emission steelworks, such as Hydnum in Puertollano, need a stable and predictable demand to expand production and become more competitive.
“The prospect of a stable demand could be decisive for some of Europe’s most advanced industrial companies”
The regulation will also include measures to expedite the granting of permits for industrial facilities in certain sectors and impose conditions on certain foreign direct investments (FDIs), so that they contribute to local job creation, technology transfer, and joint-ownership structures. A notable example is the Stellantis-CATL joint venture in Zaragoza, 50% owned by each company and expected to employ 4,000 local workers. The Commission’s proposal, unveiled in March, is currently in negotiations in the European Parliament and the Council. Its adoption could take place by the end of 2026 or in 2027.
The objectives of the regulation — supporting Europe’s strategic industries through domestic demand, shortening permit timelines, and conditioning foreign investment to maximize benefits — have earned broad support among national governments and political parties. However, disagreements persist on details that could determine the initiative’s success or failure. The industry needs clear expectations about demand and investment to expand its productive capacity in Europe, and half-measures or good intentions will not suffice.
“The industry needs clear expectations about demand and investment to expand its productive capacity in Europe, and half-measures or good intentions will not suffice”
The March 2026 proposal from the Commission reflects a political commitment that has somewhat diluted the scope of its industrial measures. It includes numerous exemptions and flexibilities, confines its main provisions to a small portion of the market, and extends the European manufacturing criteria to a broad set of third countries. All of this could produce a weak rule with limited capacity to stimulate demand, potentially favouring investment in third countries rather than boosting investment in the EU.
What does “Made in Europe” mean in the new law?
One of the main points of contention has been the geographic scope of the regulation. Defining which countries should be included in the definition of “Made in Europe” has proven particularly tricky. Some governments want to include all trading partners, while others prefer to limit it to the Member States. The current proposal includes the twenty-seven EU countries, as well as those that have signed a free trade agreement or customs union with the Union, or are part of the WTO Agreement on Government Procurement, depending on the type of public intervention and applicable conditions. In total, around 90 countries.
For the regulation to have real effects, the definition of “Made in Europe” cannot cover too many countries, especially if some of them could undermine the EU’s competitiveness. Reciprocity in how European companies are treated in third countries is a fundamental factor, since most of the Union’s trading partners already apply policies that favor domestic production to support their own industries. It is also essential to adopt measures that prevent circumvention and to avoid allowing major powers to invest in countries included in the “Made in Europe” definition so they can later export to the single market, profiting from public subsidies.
“For the regulation to have real effects, the definition of «Made in Europe» cannot cover too many countries, especially if some of them could undermine the EU’s competitiveness”
In fact, Chinese foreign direct investment has surged in recent years in several countries near the EU, such as Morocco, Serbia, and Turkey, especially in the sectors covered by the Industrial Accelerator Act. This raises the risk that Chinese companies will manufacture batteries, electric vehicles, and other clean technologies in those countries for export to the EU, thereby weakening the law’s effectiveness.
Negotiations in the European Parliament and the Council
The co-legislators — the European Parliament and the Council — are preparing their negotiating positions. In the Parliament, the draft report prepared by MEPs from the Socialists & Democrats, Renew Europe, and the Greens includes numerous measures aimed at strengthening the regulation. The amendments from the various groups show broad centrists consensus on the initiative’s priorities.
The European People’s Party (EPP) is much more divided. Some of its MEPs have submitted an amendment to reject the regulation entirely, while its alternate rapporteur in the ITRE Committee proposes changes to strengthen it. The Spanish EPP delegation appears to broadly support the initiative and is seeking to reinforce its main measures. It seems likely that the European Parliament will approach negotiations with a firm position in favor of a regulation that delivers real effects.
In the Council, negotiations focus on defining the criteria for European manufacturing. The pioneer markets policy envisioned by the regulation would benefit the entire Union by generating growth and employment, especially in countries with substantial industrial capacity such as the Czech Republic, Slovenia, Slovakia, Hungary, Poland, or Germany. Almost all national governments have expressed support for the regulation’s objectives, though disagreements remain on certain specifics. In particular, the geographic scope of the European manufacturing criteria and some of the exemptions envisaged in the Commission’s proposal dominate the talks. Spain has played a key role in this debate. As one of Europe’s leading hubs of clean-tech industries, it stands to gain significantly from the Industrial Accelerator Act.
France and Germany have reached a preliminary agreement on the provisions of the regulation related to the automotive sector. The drafts indicate that the two countries have aligned their positions around strict European manufacturing criteria, albeit with room to include other countries. This agreement could pave the way for the regulation’s approval, provided it guarantees support for the strategic links in the value chain, including batteries, and extends this approach to the rest of the sectors covered by the regulation.
“This agreement could pave the way for the regulation’s approval, provided it guarantees support for the strategic links in the value chain, including batteries”
Both the Commission and the Council have expressed their readiness to conclude negotiations before the end of the year. While that deadline may be optimistic, it is clear that the EU intends to pass the Industrial Accelerator Act in the coming months. The law is being debated at a decisive moment for Europe’s strategic industries. Its final content and its approval could significantly influence the profitability of investing and manufacturing in the EU over the next decade. With several national elections planned for 2027, time is pressing to approve an effective industrial policy that Europe’s strategic sectors urgently need.