Expect the incoming Democratic majority to keep a close watch on how prediction markets price the landscape.
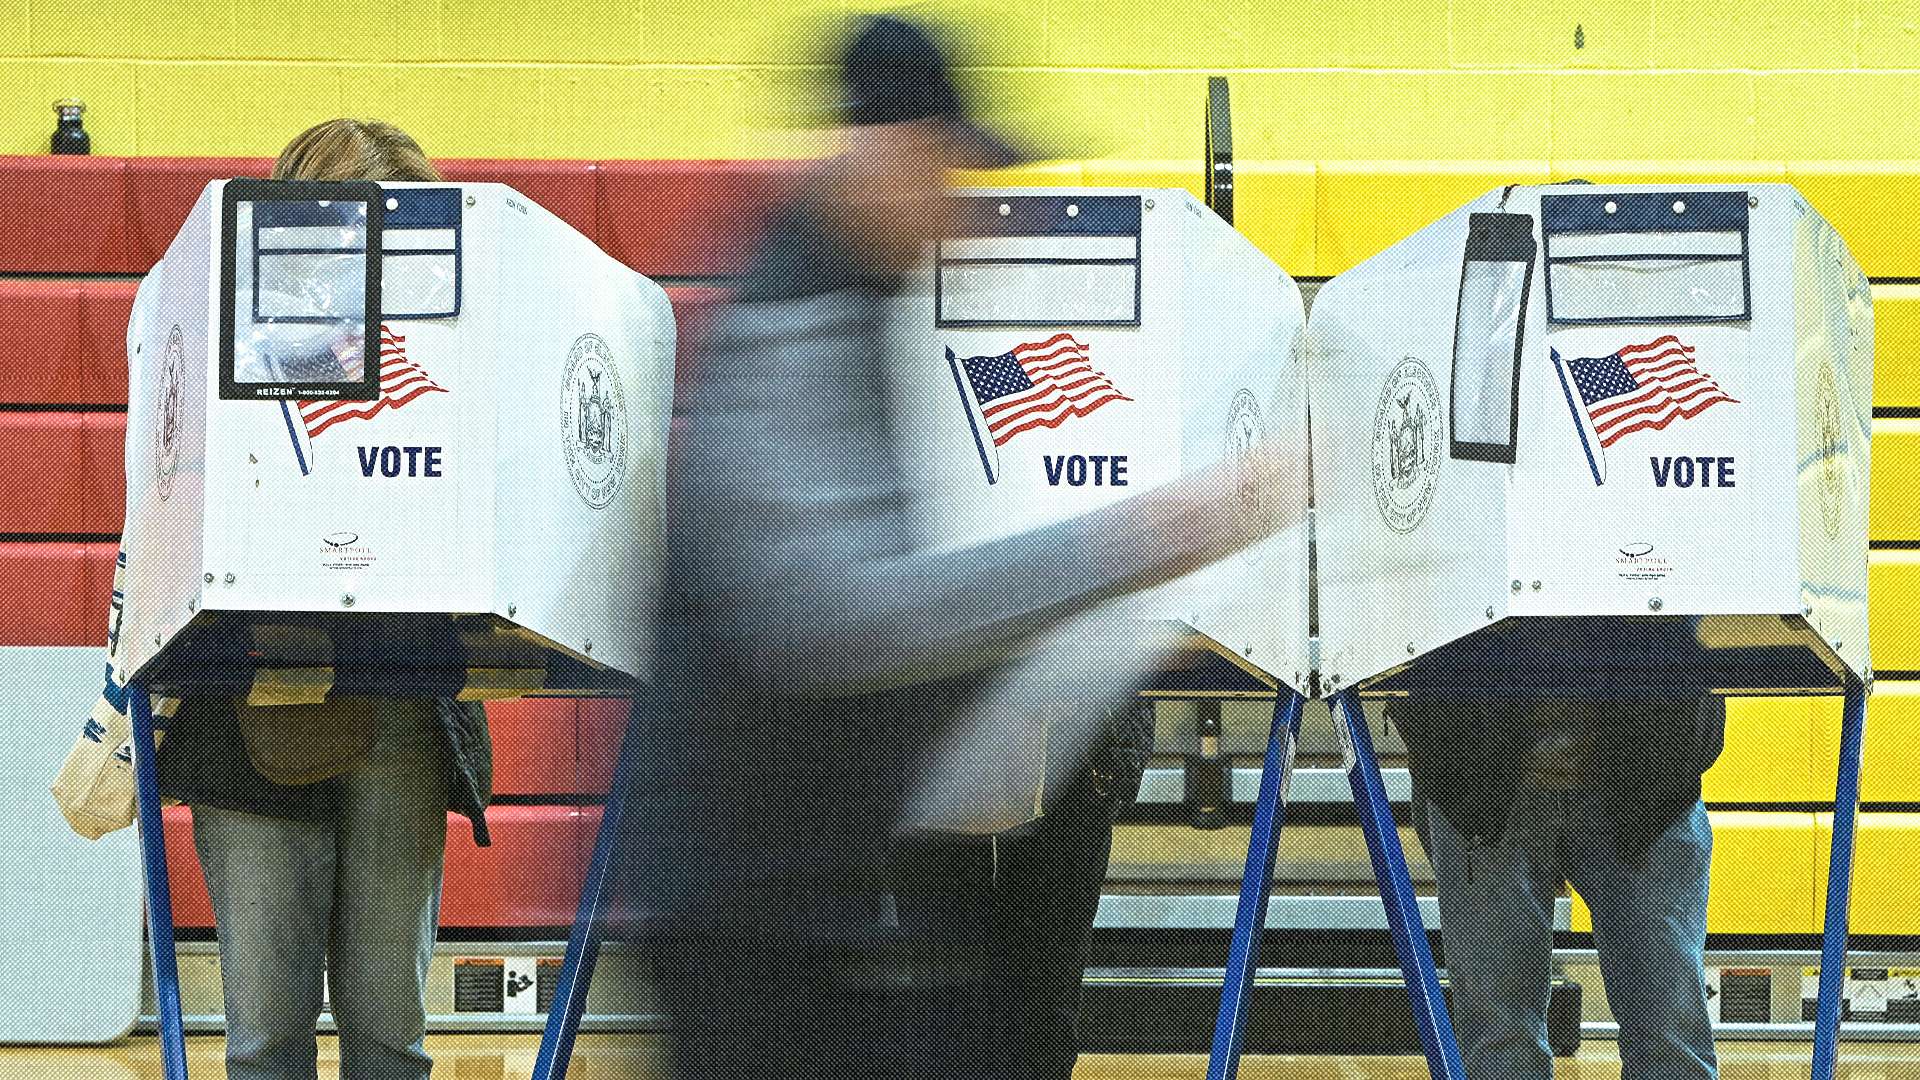
Democrats had a strong week, seizing control of both the House and the Senate with relative ease. Yet one often overlooked beneficiary of the so-called “blue wave” is the growing role of prediction markets, which are steadily becoming a fixture in American elections.
By late Monday, Americans had bet nearly $1.9 billion on midterm outcomes, wagering on more than 7,000 distinct possibilities, according to The Washington Post. As early as April, participants on Polymarket and Kalshi were pricing a blue wave—Democrats winning more than 235 House seats and at least 51 Senate seats—at just over 50 percent. On PredictIt, a comparable blue-tsunami market traded at about 66 cents the morning of election day, while traders on Kalshi and Polymarket placed probabilities above 70 percent.
Moments before the first ballots were counted on election night, premier prediction markets such as Polymarket and PredictIt had already forecast that Democrats would seize control of both chambers, with the House odds exceeding 90 percent. By Wednesday morning, Kalshi’s leading market had correctly anticipated 479 of 487 midterm races. “That’s 98%, forecast before a single vote was tallied,” the platform noted on X.
For prediction markets, accurately pricing electoral outcomes does more than confer legitimacy; it also helps the platforms to be seen as something beyond a mere sports-bet framework—a label some lawmakers have applied to them. Paradoxically, the sheer volume of trading on election markets—$2.5 billion on Kalshi alone, compared with about $1.3 billion traded during the 2024 elections—may familiarize Americans with these platforms, but it is also likely to draw heightened scrutiny from lawmakers in both parties who worry about the systems’ impact on the democratic process.
Rep. Blake Moore (R–Utah) expressed his concerns about insider trading to The Washington Post. “People are going to take advantage of this,” he warned. “Individuals who can influence elections, consulting firms, polling outfits, staff for candidates—all of them will know how to game the system.” Moore, along with Rep. Jamie Raskin (D–Md.) and Sen. Jeff Merkley (D–Ore.), has proposed legislation to prohibit election contracts and trades tied to electoral outcomes.
Even with alarm among some lawmakers, some experts contend that election contracts do not pose an inherent risk to election integrity. “I see traditional polling and prediction markets as complementary,” argues Thomas Kingsley, director of financial services policy at the American Action Forum.
Kingsley notes that focusing on who is ahead or who is winning in these platforms is somewhat reductive, since prediction markets and polling serve slightly different functions. Conventional polling models—such as The New York Times/Siena, AtlasIntel, Emerson College—as well as forecasts like Nate Silver’s FLIPR, provide a static snapshot of voters’ intentions. By contrast, prediction markets reflect the public’s expectations in real time.
What these markets deliver, Kingsley emphasizes, are probabilistic estimates. A market pricing an outcome at 55 percent implies that the event should occur roughly 55 percent of the time. In that sense, the markets performed reasonably well. They did not foresee Democrats winning the Senate race in South Carolina, nor did traders expect Gina Hinojosa to win Texas’ gubernatorial contest. Yet traders did view races in Iowa and Kansas as toss-ups heading into Election Day. In Kansas—where a Democratic senator had not been elected in 94 years—the odds appeared quite favorable.
The performance of prediction markets during the election is unlikely to sway the Democratic majority, which will soon possess subpoena power to compel private-company executives to testify; they have already signaled they might use it. Senator Elizabeth Warren (D–Mass.), widely anticipated to chair the Senate Banking, Housing, and Urban Affairs Committee, has been openly antagonistic toward the industry.
In a letter sent to the CEOs of Polymarket and Kalshi days before the election, Warren and Senator John Curtis (R–Utah) argued that despite the markets’ self-policing against insider trading, they remained skeptical that the platforms could “sufficiently police these contracts with effective scrutiny and meaningful accountability.” They noted that the cases the prediction markets did catch raised “serious questions about how much similar activity may be going undetected,” and urged the executives to respond by election day.
(Kalshi is a supporter of Reason Foundation, the nonprofit that publishes Reason.)
“Overseeing these products is not a matter of debate,” Kingsley contends. The U.S. Commodity Futures Trading Commission (CFTC) already holds regulatory authority over futures exchanges, including designated contract markets such as prediction markets; Congress granted that authority to the agency.
Beyond Curtis and Warren, a broad coalition of state regulators—from Utah, New York, Minnesota, and Arizona—are pursuing legal challenges against prediction markets for allegedly violating state gambling laws. Those challenges could intensify if federal lawmakers succeed in their aims.
In June, 17 Senate Democrats, including Warren, Merkley, and other members of the Senate subcommittee that oversees the CFTC, signaled what may come next. In a letter to the subcommittee chair, the senators urged Congress to prevent the CFTC from using federal funds to finance lawsuits against states and tribal governments that have moved to regulate prediction markets. They described prediction markets as “no different than gambling” and argued that by suing state regulators for overstepping jurisdiction, the CFTC risks becoming an instrument that helps online prediction markets evade state protections, potentially triggering a race to the bottom in gambling oversight.
The midterm showing has enhanced the legitimacy of these platforms. But Kingsley cautions that whether prediction markets amount to gambling is a philosophical debate. Alas, in the new congressional majority’s view, it may no longer be a matter of interpretation.
The Federal Government Once Tried To Restrict Prediction Markets. Now It’s Suing States To Save Them.