Much of the hostility aimed at private equity is effectively a familiar opposition to free markets dressed up in alarm.
In 2024, Blackstone—the globe’s largest private-equity firm at that moment, managing roughly $1 trillion in assets—announced its intention to acquire Jersey Mike’s, a sandwich chain built from a single shop on the Jersey Shore in 1975 by a 17-year-old Peter Cancro who had bought the first storefront with a loan secured from his high‑school football coach. Jersey Mike’s had evolved into one of the speediest‑growing restaurant brands in the United States.
If you hail from New Jersey the way I do, you may feel a twinge of skepticism about the brand’s willingness to cloak itself in something of a regional authenticity, since The Original Italian doesn’t quite reflect the range of New Jersey cured-meat artistry available at places like Dolce & Clemente’s in Robbinsville, Michael’s Salumeria in Lyndhurst, or Fiore’s House of Quality in Hoboken. Still, the sandwich holds up—reliable, sturdy, and less dismal than a fading Subway footlong.
Perhaps inevitable, then, was the surge of social‑media chatter after the Blackstone purchase, with enthusiasts complaining that portions shrank and quality dipped. One TikTok user held up what he claimed was a $9 sandwich and told the camera, “This is what $9 buys you.” The posts circulated widely on Instagram and Reddit, drawing coverage from outlets from Yahoo! Finance to the food‑ranking site Sporked. An Instagram Threads user even proclaimed, before tasting anything, that “private equity destroys everything it touches” and that the brand would be “sold for parts within five years.”
@dionckhan #AmPm #JerseyMikes #LunchLady I shoulda went to Firehouse!
♬ original sound – Dion IKhanic
The uproar was pronounced enough that the newly installed CEO, Charlie Morrison, publicly acknowledged that he was “well aware of the often‑negative perception surrounding private equity firms, especially in the food business,” and that he was monitoring the complaints.
Yet nothing about the product or the price changed—the sandwiches remained the same, and there was no plan to “rethink” the brand. “We’re not going to reconfigure, re‑engineer, or alter the brand. That’s not in the cards,” Morrison stated.
Jersey Mike’s sales rose by more than 10 percent in the first year after the Blackstone buyout, and in July the company went public, raising $1 billion—the largest consumer IPO in the United States that year. Today the brand has expanded with hundreds of new outlets, and in 2026 it surpassed Chick‑fil‑A in the American Customer Satisfaction Index, ending an 11‑year streak for the fast-food leader.
This arc is familiar to critics who view private equity with contempt. Opponents such as the Private Equity Stakeholder Project, ProPublica, and other seasoned dissenters on the left argue that private equity is merely another variant of predatory capitalism: “vampires” engaged in “legalized looting,” in the words of Senator Elizabeth Warren, and “vultures” driven by “corporate greed at its most revolting,” in the framing of Senator Bernie Sanders.
They marshal a wide array of bogeymen to bolster their case, pointing to private‑equity reach into everything from hospitals to prisons to for‑profit schools, all while their reliance on financing tricks—like “leasebacks,” “roll‑ups,” and “dividend recapitalizations”—is said to siphon billions for a handful of insiders while leaving the companies that sustain workers and customers in a zombie-like state.
What these critics want you to believe is that private equity is uniquely malign, a venomous form of hypercapitalism. But a careful look at case studies and a broad review of the evidence paints a more nuanced picture. Private equity isn’t a cure‑all, and it’s not without flaws. But from Italian subs to nursing homes to state pension funds, it offers substantial value for both capital providers and consumers. Seen in this light, a lot of the hate aimed at private equity is simply a conventionalist view skeptical of free markets.
Bond, Junk Bond
What we now call private equity traces back to the 1980s, when a loose coalition of financiers popularized leveraged buyouts. In plain terms, a leveraged buyout occurs when a group of investors secures majority control of an existing company by tacking a large amount of debt onto a relatively small equity base.
A pioneering advocate of this new financial structure, Michael C. Jensen of Harvard Business School, argued that replacing a diffuse base of scattered shareholders with a small cadre of highly incentivized owners would push organizations toward leaner operations, cut overhead, tighten management, and, naturally, boost profits.
But that early wave of raiders included the flamboyantly rolled‑hair‑style icon Michael Milken and his firm, Drexel Burnham Lambert. Milken demonstrated that debt issued by riskier or smaller firms—those lacking investment‑grade credit ratings—could yield sufficiently high yields that a diversified portfolio of such bonds could outperform safer issues even after defaults were counted. This discovery provided the fuel for a boom in leveraged buyouts. You borrowed against a company you hadn’t yet bought, used that money to acquire it, and paid the debt back from the acquired company’s cash flows. It was massively profitable and, as some alleged, occasionally criminal. Milken pleaded guilty to securities fraud in 1990, and Drexel Burnham Lambert collapsed the same year. The market for junk bonds that powered the enterprise dissolved, ending the first wave of leveraged buyouts.
Yet, as with other disruptive technologies, leveraged buyouts reappeared with renewed vigor about a decade and a half later, marking the true onset of the modern private‑equity era.
The contemporary private‑equity firm operates through what the industry calls “closed‑end funds.” Consider them akin to film‑production companies created for a specific project and dissolved when the project finishes—whether or not it ever secures a distributor.
Private equity funds focus on companies rather than scripts, but like many indie‑film funders, a private‑equity fund is structured as a limited partnership (L.P.). Here, two kinds of stakeholders exist: the fund’s “general partners” (G.P.s), who serve as the decision‑makers and overall vision, and the “limited partners” (L.P.s)—ranging from pension funds and university endowments to wealthy individuals—who provide capital but do not partake in day‑to‑day governance.
Private equity funds are designed to run for a fixed horizon, typically about 10 years, after which the general partners must exit their stakes by selling or otherwise disposing of the underlying asset, called a portfolio company, so that everyone can “get rich.” The ten‑year frame is meant to curb short‑termism and liquidity obsessions that plague large public corporations, while shielding private equity from reflexive runs and aligning management incentives with investors around real value creation rather than chasing paper profits.
In part, private equity exists to tackle managerial and operational challenges common to publicly traded peers. They bring governance incentives to bear; the critique of boards at sluggish public companies is that they resemble bureaucratic committees more than profit‑driven bodies. Private equity ownership, by contrast, places a small cadre of highly motivated decision‑makers in the room with the authority to take productive actions.
When the plan goes according to the script, we get comeback stories about familiar brands.
KKR—an archetypal “white‑shoe” private‑equity firm with a robust leadership network that once counted former CIA director and ex‑Army General David Petraeus among its senior partners—acquired Dollar General in 2007 when the retailer was underperforming, retooled its operations, and brought it back to public markets with strong results.
Blackstone, the engine behind Jersey Mike’s, bought Hilton Hotels in 2007 for $26 billion, a landmark deal at the time. It brought in new leadership, restructured operations, expanded growth, and led the chain to a public listing in 2013, recording substantial gains. It remains one of the most profitable single‑asset private‑equity investments ever made.
Silver Lake, another heavyweight and a tech specialist, took Dell private in 2013 for $24.4 billion—freeing its founder, Michael Dell, to pursue long‑term investments rather than quarterly earnings calls. Dell went public again in 2018 and now carries a market value around $300 billion.
Domino’s Pizza, Dunkin’, and a string of other names followed. In each case, what private equity brought to the table was less magic and more what practitioners describe as “pattern recognition”—the ability to scan dozens of portfolio companies across time and extract lessons that no single business could have learned on its own.
That does not mean every private‑equity takeover of a beloved brand ends smoothly. Critics repeatedly point to well‑known retailers that faltered after leveraged buyouts. Toys “R” Us spent about 97 percent of its operating profit on debt service before bankruptcy. Red Lobster’s sale‑leaseback drained cash by selling real estate and then renting it back, salvaging investor capital but contributing to a bankruptcy. Payless reportedly paid hundreds of millions in dividends to its private‑equity owners before its 2017 bankruptcy.

Private‑equity practitioners do not pretend there aren’t misfires. Debt can lift already strong firms, but it can also magnify the misfortune of weak ones. In a world where Amazon disrupted retail, Toys R Us and Payless lacked the financial flexibility to adapt. The debt—regardless of market disruption—still had to be paid.
But what about the averages? A 2016 study examined ten years of private‑equity influence in the restaurant sector. The research by Shai Bernstein (then at Stanford) and Albert Sheen (then at Oregon) stood out for using a solid, objective gauge of improvement—health‑inspection records—that also resists the claim that private equity owners are short‑term profiteers at the expense of customers. The study found that restaurants under private equity management improved: health violations dropped by about a quarter, cleanliness and upkeep rose, and these changes correlated with more customers and fewer outbreaks.
Bernstein and Sheen also assessed chains with both franchisee locations and parent‑operated units, discovering that parent‑run outlets progressed more than franchises. In short, the link between private equity and operational gains appears more causal than merely correlational.
The authors also observed that private‑equity firms whose partners have direct restaurant‑industry experience tended to perform better than those led by partners with only financial training. That, in fact, is private equity’s core value‑add in consumer sectors: managers who are well connected to operators in the field and who can draw on deep sector expertise that no single portfolio company could amass on its own.
Sheen and colleagues later produced a broader paper on private equity’s effects on consumer products in general, titled “Barbarians at the Store? Private Equity, Products, and Consumers.” Building on the famous Barbarians at the Gate case study of the 1980s leveraged buyout of RJR Nabisco, that work notes that the big deal did not only symbolize excess but also shaped how critics view the whole model today.
Yet the paper’s results are noticeably optimistic: after a private‑equity deal, target brands see retail sales grow about 50% faster than comparable firms. Price increases—roughly 1% on existing lines—do not drive this growth; instead, new product launches and geographic expansion do. Competitors tend to pare back their product lines and push prices slightly higher in response.
The study also found that companies that had been publicly owned before the private‑equity deal showed smaller gains. The authors suggest, quite naturally, that smaller, younger private firms have more room to grow via geographic expansion, new lines, and more aggressive marketing. In contrast, mature public companies lack the flexibility to achieve similar growth. “This variation in outcomes helps explain the media’s negative portrayal of private equity: layoffs and downsizing are the most visible, high‑profile targets.”
That explanation seems plausible and invites a broader thought: perhaps large, sluggish publicly traded firms create more value for consumers by being dismantled and sold in pieces. It’s a source of frustration for anti‑capitalists, but a routine feature for capitalists who do the work.
Private Equity as Landlord
Inflation, the squeeze on living costs, and a pervasive sense among younger Americans that the postwar dream remains out of reach have turned private equity’s forays into bulk housing purchases into a significant political liability. The phenomenon exists in reality, but public concern often overstates its reach and is fueled mainly by business practices not unique to private equity.
In the wake of the 2008 financial crisis, some private‑equity outfits did amass homes in bulk in distressed markets, snapping up foreclosures and short sales at bargain prices and turning them into rentals, thereby creating a new corporate landlord sector that hadn’t existed before. By some accounts, these moves helped shore up collapsing home values while limiting would‑be buyers’ ability to snap up properties at the bottom of the market, according to a 2024 Government Accountability Office report.
In recent years, anecdotes and press reports have highlighted maintenance backlogs, sluggish responses, and aggressive fees from PE landlords. This climate even produced lawsuits from tenants, along with the Department of Justice and several state attorneys general, against corporate landlords and RealPage, a software company that aggregates data from multiple institutional owners to set rents algorithmically. The government argued that this amounted to coordinated price fixing. Two rounds of tenant lawsuits have yielded settlements totaling nearly $360 million from landlords to date. The DOJ action, started under President Biden, concluded with the Trump administration proposing a settlement with RealPage in November 2025, wherein RealPage agreed to stop training its product on nonpublic data from ostensible competitors.
But if that is price fixing, it would be illegal whether the firms behind it are private‑equity owned or not. Only one of the named defendants in the RealPage case was PE‑owned, with the rest spanning both public and private ownership structures.
More broadly, PE’s footprint in the residential market remains small in relation to the level of public concern it generates. Institutional investors in general—including publicly traded real estate investment trusts (REITs), PE‑backed platforms, and other corporate landlords—own roughly 3 percent of the nation’s single‑family rental stock, with an even smaller share when looking at all single‑family housing, according to a 2023 study.
PE specifically owns only a portion of that—by its own accounting, Blackstone controlled roughly 62,000 of the 106 million single‑family homes in the United States, and new acquisitions have dropped by around 90 percent since 2022. If this once looked like a lucrative market for headline‑grabbing partners, the appeal has clearly waned.
The broader reality is that America’s housing affordability crisis arises from a multitude of factors, including onerous zoning rules and permitting bottlenecks, rising construction costs, and the entrenched resistance of current homeowners to growth and change—often labeled NIMBYism. These forces predate institutional single‑family investment by decades and do not hinge on private‑equity stakes.
In fact, the story progressives often tell—that PE‑owned houses pushed prices higher and made affordable housing impossible—may be backward. Housing became a magnet for PE because constrained supply made residential real estate a reliable appreciating asset. The flip side is that private‑equity buyers retreated when interest rates rose and credit markets tightened in recent years, underscoring that PE players respond to incentives rather than wielding tyrannical control over the system.
The Wages of Death
If the critique of private equity can be pointed at something within the home, try the debate over its growing stake in health care—especially the “roll‑ups” of independent medical practices and the investment in nursing homes.
A large, carefully controlled 2021 study led by the University of Pennsylvania’s Atul Gupta found that PE ownership of nursing homes correlated with an uptick in short‑term mortality among patients, while facilities selected sicker patients at higher risk showed more ambiguous results. The finding was troubling, but the authors note that the effect persisted whether the PE firm took over existing chain operators or consolidated a group of independents, implying that the act of consolidation itself isn’t the sole culprit.
Interestingly, facilities owned by PE that admitted more patients per bed than the median tended to have better mortality outcomes than those admitting fewer, suggesting that cramming more patients isn’t inherently worse when managed well. The authors attribute the negative outcomes for lower‑risk patients to a modest cut—about 3 percent—in nursing‑assistant hours at PE‑run homes. Since nursing assistants perform essential tasks—from mobility support to infection prevention—their reduced presence could plausibly affect recovery and well‑being. However, PE‑owned facilities that employed more registered nurses, who deliver direct medical care, did not show the same negative results among high‑risk patients.
What’s more, most nursing homes rely heavily on Medicare funding, with taxpayers covering a large share of costs. The data show that the more Medicare revenue a PE‑owned facility depends on, the worse its outcomes tend to be. That finding invites a straightforward question: Is the fault PE, or the broader government‑driven model that separates patients from payers and relies on a sprawling, error‑prone bureaucracy?
Even as Gupta and colleagues stress that restricting PE ownership of nursing homes could “save lives,” they caution that such limits would not be a cure; they could also discourage the creation of new facilities, potentially harming long‑term health outcomes. Steven Kaplan, a University of Chicago economist who is often skeptical of PE’s gains, notes that many nursing home deals in the data lost money, implying that some of the observed costs may reflect misjudgment rather than misdeeds.
More broadly, a systematic review published in The BMJ—an outlet not typically friendly to the industry—summarized decades of empirical work on PE‑owned health care. The headline is unflattering: higher costs to patients and payers are the most consistent finding. On mortality and other health outcomes, the evidence is mixed: eight studies reviewed yielded two showing benefits, three showing harms, and three that were neutral. Some studies do report improvements, such as better patient access to care and lower operating costs; others show reduced in‑hospital and 30‑day mortality for certain heart‑attack cases in PE‑owned hospitals, or enhanced pneumonia outcomes in PE facilities.
Looking beyond nursing homes to outpatient care, a 2022 JAMA Health Forum study found that PE acquisitions of physician dermatology, gastroenterology, and ophthalmology practices were associated with higher patient volumes and higher charges per claim. How to interpret this? Is it PE’s drive to upsell and extract more from insurers, or simply better access to care for more people? Advocates of subsidized or single‑payer health systems argue the former can be a virtue if it expands coverage, while others worry about the system’s incentives that drive up utilization and costs.
One way to view the mixed record is to see PE’s operational and financial engineering as optimized for criteria that are easy to measure and reward—revenue, volumes, and explicit quality metrics—while potentially underinvesting in less tangible, diffuse care that matters just as much but is harder to quantify.
Another plausible reading is that PE in health care is less about trimming costs and more about navigating a system where the bulk of costs are subsidized by third parties rather than charged directly to patients. That is not a blanket indictment of PE, but rather a critique of how our health‑care system creates incentives that shape behavior. Stakeholders respond accordingly.
What Private Equity Is and What It Isn’t
It helps to take a step back and ask what private equity is meant to do, what the evidence shows it does overall, and who tends to benefit from private‑equity profits.
Private equity funds exist to deliver superior returns to their investors. Those investors aren’t merely a club of unrelenting rich people.
The two largest PE backers in the United States are CalPERS and CalSTRS—the California Public Employees’ Retirement System and the California State Teachers’ Retirement System. Together, they have allocated on the order of $150 billion to the asset class.
CalPERS alone manages funds for more than 2 million California public workers, retirees, and their families. When private equity does well, the gains flow back to many of the very groups that critics like Sanders and Warren tend to praise.
That means Sanders, Warren, and their allies who criticize PE should find some satisfaction in the data showing PE has delivered solid relative returns compared with many benchmarks. A series of studies led by Kaplan and colleagues indicates that private‑equity funds outperformed the S&P 500 by roughly 3 percent a year from their birth in the 1980s through the 2008 financial crisis. A 2026 McKinsey report focusing on the top quartile of PE funds found a 24 percent return over the preceding decade, versus 15 percent for the S&P 500. Cambridge Associates’ PE index likewise suggests the sector outperformed both the S&P 500 and the Russell 2000 in recent years.
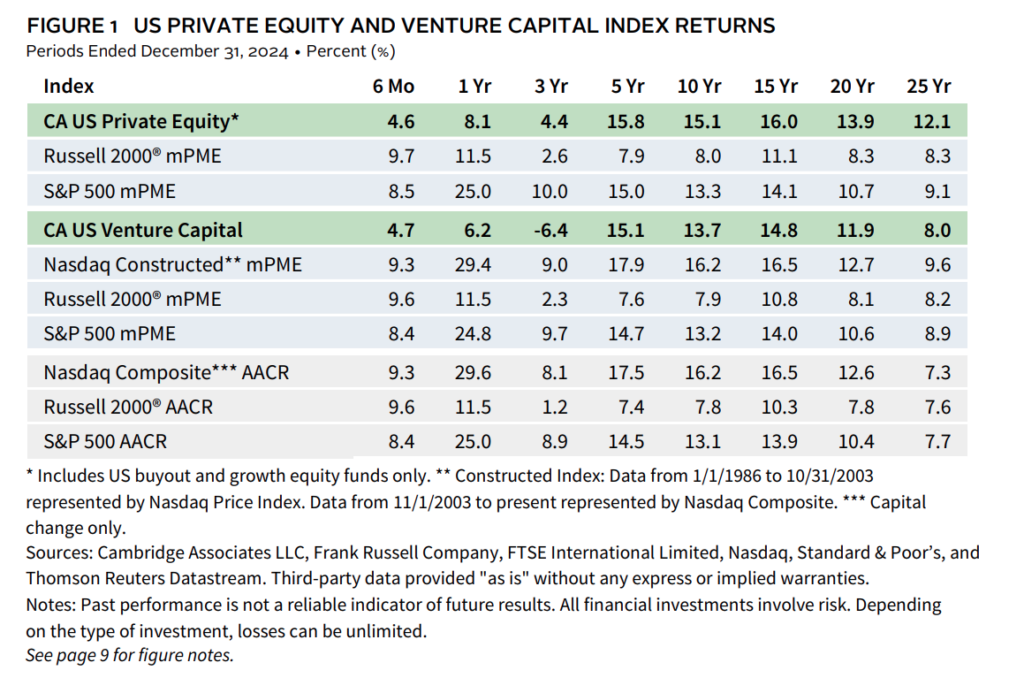
Yes, private equity’s results have become more uneven. Kaplan and colleagues note that returns relative to public indices have flattened and aren’t clearly superior to the S&P 500 for PE “vintages” after the 2008 crisis. An influential 2020 paper by Oxford economist Ludovic Phalippou—himself a critic of PE—argues that when you apply appropriate benchmarks, the outperformance of the average PE fund over public ownership largely vanishes. Most observers concede that 2022–2024 represented a genuinely difficult period for private equity.
Beyond that, Kaplan’s team argues that PE is, like much of the economy, cyclical. Private‑equity booms tend to coincide with abundant, cheap money; when interest rates rise and credit tightens—as in the post‑pandemic period—the returns slip.
This logic makes sense: if you can buy a company earning 7 percent with debt costing 5 percent, the deal looks good. If rates climb to 8 percent, the economics deteriorate.
Kaplan demonstrates that higher rates also restrain leverage: the equity portion of deals grows while debt funding shrinks. The McKinsey view summarized the same theme: “Private equity in 2026 is a mature industry—a radical shift from a decade ago. The ingredients that once amplified returns—lower interest rates, rising valuations, and ample leverage—have faded.” With tighter credit, “alpha” will be harder to conjure from market dynamics alone; it will increasingly require true expertise. In other words, when borrowing costs rise, fancy financing tricks aren’t a guaranteed route to rich rewards unless you actually know your stuff.
On that note, both supporters and critics should greet the trend with a certain relief.
As of 2025, private‑equity firms owned nearly 83,000 U.S. companies—about 3.5 percent of all private‑sector firms in the country, according to S&P Global Market Intelligence. Those businesses employed an estimated 13.3 million people in 2024, per the American Investment Council, the industry trade group. That makes private equity a meaningful, but not dominant, presence in the American economy.
If a PE outfit creates lasting value for its investors, it survives; if not, it fades away. And in either case, your next Original Italian sandwich will probably be fine.