There is a contradiction in the way Spaniards relate to their savings. The majority knows that inflation can erode the value of money kept in a bank account, but 63% do not invest in financial products. And, among those who don’t, four out of ten would like to start. The question seems simple: if there is the will, why is it so hard to take the step?
The answers aren’t limited to a lack of financial education. There is fear of risk, doubts about the products, and a trust issue that still haunts the banking sector. “There is still a wound from previous crises”, acknowledges Martos. Added to this are taxation and the difficulty of saving when salaries or access to housing already occupy a large part of people’s concerns. All this intersects with a broader problem: Europe needs to mobilize its savings to finance companies and close the economic gap with the United States.
Carlos Martos, head of Investment Products at ING, knows these barriers from the financial sector. In this interview he argues that banks and public administrations must also assume responsibility, calls for revising ETF taxation, and asks to restore incentives for retirement savings. For him, the goal is not merely to convince more citizens to invest, but to accompany them through that process. ‘We cannot hand all the duties to the client’, he says.
Martos during his participation in the latest edition of the Mission Social Contract. Photo: Courtesy
Europe saves a lot, but invests little. Why does that gap exist? Is it a cultural issue, a matter of incentives, or market design?
Europe saves far less than the United States. The amount of saving is very high and healthy, but for a series of reasons, it is not being invested. We are missing a huge opportunity because that savings is not channeled as directly toward companies as happens through investing.
That is leaving us behind in terms of competitiveness compared to the United States, where small businesses and start-ups, among others, obtain much more financing and with greater speed. We are leaving money on the table.
In Spain there is quite a bit of awareness that money left idle loses value, yet 63% of customers do not invest. How can this distance between what we know and what we do be explained?
It’s true that 63% of customers do not invest, but gradually we are realizing that inflation erodes our purchasing power.
“We are missing a huge opportunity because that savings is not channeled as directly toward companies as it is through investing”
We come from very high inflation in 2022, with the Ukraine crisis, reaching close to 10% at times. We have started to notice it in our grocery basket and in our daily lives. We are increasingly aware that we need to supplement our income.
Moreover, among those who do not invest, four out of ten would like to. That share is even higher among people aged 25 to 44. There is a very important opportunity there: the need exists and the willingness exists, but many people do not know how to do it. Fears, a lack of financial knowledge, and unfamiliarity with the products then come into play.
Precisely among those aged 25 to 44 there seems to be greater willingness to invest. What is changing in that profile and what kind of investor do you think we will see in five years?
Among young people several factors converge. The first is that there is digital access to investment products like never before. One can invest through neobanks and also through traditional banks, such as ING, with access to products from a digital platform.
These generations are also realizing that they need to supplement their income. Often salaries do not allow them to meet all life expectations, and they are beginning to understand that investment can provide a supplement, even starting from small amounts.
In addition, they do not carry as much the scar of previous financial crises and, therefore, show a greater willingness to invest. Products like ETFs appear. At ING we have bet on them: we offer more than 1,000 ETFs, of which 600 can be bought without a trading commission. We are seeing that this segment is investing.
But growth is not limited to the young. We have surpassed 25 billion in assets under management and we have more than 700,000 clients. A significant portion has come in recent years due to inflation, but also because we have had good years in the stock market and attractive returns in fixed income. All of this is encouraging people to invest.
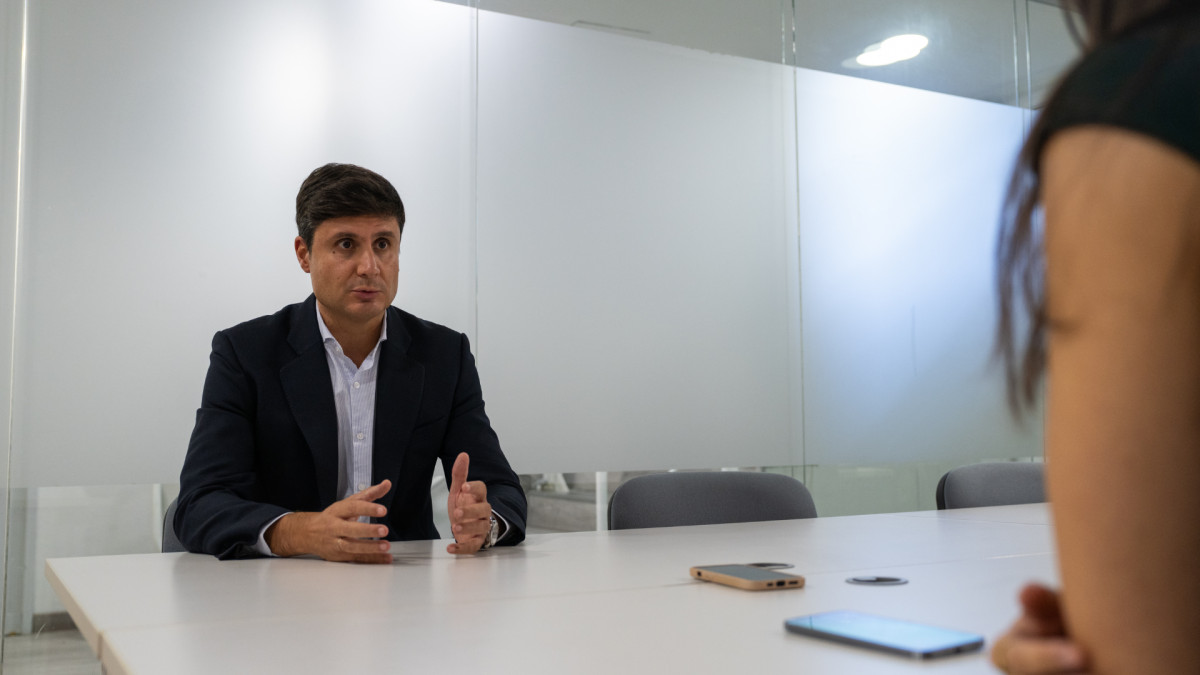
Martos explains the different investor profiles and the proposals for each of them. Photo: Courtesy
At the other end are those approaching retirement. There is concern about the future of pensions, but few people invest specifically with that stage in mind. How should responsibility be distributed among individual savings, companies, the financial sector and the public system?
It has to be a combination. We cannot center everything on employment plans, on the individual responsibility of citizens, or on the financial sector. All must intervene.
There is a need for a lot of education so that the client understands that they also have a responsibility in saving for their retirement. There are also employment plans that have been promoted and, from the financial sector, we also have to contribute.
“There is a need for a lot of education so that the client understands that they also have a responsibility in saving for their retirement”
In recent years, contributions to pension plans have fallen a lot. Taxation has changed and that creates friction for the client. It used to be very common to invest at the end of the year in a pension plan because the tax incentives were evident. Now it is not the case.
There are other avenues, such as mutual funds or ETFs, but I think financial institutions also need a bit of help.
Among the barriers to investing, lack of financial education, risk aversion, cultural factors, taxation and lack of trust are cited. Which are easier to overcome and which require longer-term work?
I would highlight three: education, trust and taxation.
Education starts in school: explaining from a young age how money works, why it is important to invest, or what it means to undertake. Public institutions have to help, and so do financial entities, but it is a social change and will probably take longer.
The second issue is trust. Here we have a special responsibility as financial entities. There is still a wound from previous crises and we must offer, especially to new generations, simple and understandable products.
We should not talk to the client only from the product and ask them to trust, but start from their needs. Why do they want to invest? Financial planning is very important. They may want to save for their children’s studies, obtain additional income, or prepare for retirement. There are different life moments and we have to offer simple solutions tailored to each need.
“We should not talk to the client only from the product and ask them to trust, but start from their needs”
And then there is taxation. The capacity of public authorities to act is much more direct there. ETFs, for example, have a tax handicap. If that friction were removed, their use would likely grow much more across different segments of society.
Is there a risk of placing too much responsibility on citizens under the argument that they need more financial education? Where does the responsibility of the public sector and the entities themselves remain?
We cannot hand all the duties to the client nor transfer all responsibility to society. We must work on education, from schools, and by providing information. On our website, for example, we offer content that explains everything from what inflation is to how certain financial products work.
But simply providing information and hoping the client makes the entire journey alone is not enough. The entities also have to guide them when investing: understand their goals, explain which product can best fit them and why. As the client progresses in that process, they also learn.
“Providing information alone and hoping the client makes the entire journey by themselves is not enough”
Therefore, we cannot leave all responsibility to schools to shape this or to clients to read. We must accompany them.
Showing high standards of the institution’s work, Martos advocates for advancing financial education in society. Photo: Courtesy
What message should the financial sector convey to provoke cultural change and broaden investment to a larger portion of Spanish society?
The message should be that we are here to help the client throughout their life.
When a person is young, they may want to achieve extra profitability; later they may be thinking about their children or other goals. Just as a bank helps buy a home through financing or a mortgage, it should also help achieve other financial goals.
If the client feels that they have been guided and advised, that they understand the products they contract and also know their risks, we can regain part of the trust.
We have to convey that investing can be a tool to help people achieve their objectives.
What two or three reforms should the public sector push in the short term to foster that change?
Three come to mind.
The first concerns ETFs. I think their taxation should be reviewed. They are simple products, with daily pricing and an ever-expanding range of options tailored to different profiles. They should have a transfer regime with tax deferral similar to that of mutual funds. In other European countries where ING operates they are very successful, and in Spain their development has been slower.
“They should have a transfer regime with tax deferral similar to that of mutual funds”
The second is pensions. We need to reestablish the habit of citizens investing every year a small amount for their retirement. We cannot rely entirely on employment plans because, looking at the data, they are not reaching the volumes previously seen in private plans.
The third area is savings or investment accounts being proposed at the European level that have had success in some countries. In Spain we have precedents like the housing accounts. If we want to encourage investment, this type of vehicle can offer an additional incentive or remove some of the frictions that exist today.
If a larger portion of European savings becomes investment, which sectors should it be directed toward so that it benefits both investors and the economy?
I don’t think we should point to a single sector, because that would imply taking a tactical position about what will work best tomorrow. That is not what clients need.
They need long-term growth trends, diversification, and risk reduction. There are many sectors with potential: artificial intelligence, technology, energy, or the financial sector itself.
In general, we need to invest in areas that contribute to the economic development Europe needs. What matters is investing in Europe, in a diversified way and with a long-term perspective.
How does that call to invest fit with the housing crisis, especially for those who have trouble even saving enough for a down payment? Could it raise risk aversion?
I think we need to flip the argument. Investing can help achieve certain goals.
It’s true that with little savings you can’t buy a home, but putting that savings in motion from the moment it starts to accumulate can help reach that objective.
The rise in housing prices in recent years creates an additional need for part of the population who wants to buy a house. Investment can be a tool to increase wealth, always being very careful with the timelines.
“Investment can be a tool to increase wealth, always being very careful with the timelines”
If someone wants to buy a home next year, obviously they should take that into account. But, by adjusting the time horizon, the risk and the product, investing can help approach that goal.
If we were to resume this conversation in five years, what indicator would allow you to say that Spain has truly moved from a saving culture to an investing culture?
The number of investors would be the main indicator. I would like to see in five years that we have closed the gap with the United States and also check whether that change has helped accelerate GDP growth.”
We have an ING study that suggests that if, in the last twenty years, only 25% of deposits had been invested, Europe would have more than a 7% additional gross domestic product.
In five years I would like to verify whether clients have invested, whether they have achieved their goals and objectives, and whether, at the same time, the economy has benefited as well.
Many thanks.
In partnership with: